How to Calculate Sugarcane Juice Business Break-Even

Table of Contents

To calculate a sugarcane juice business break-even point, divide total fixed costs by the contribution margin per serving. This guide explains the formula, cost inputs, sales assumptions, ROI considerations, and practical ways to build a reliable break-even model for a commercial juice operation.

The Basic Sugarcane Juice Break-Even Formula
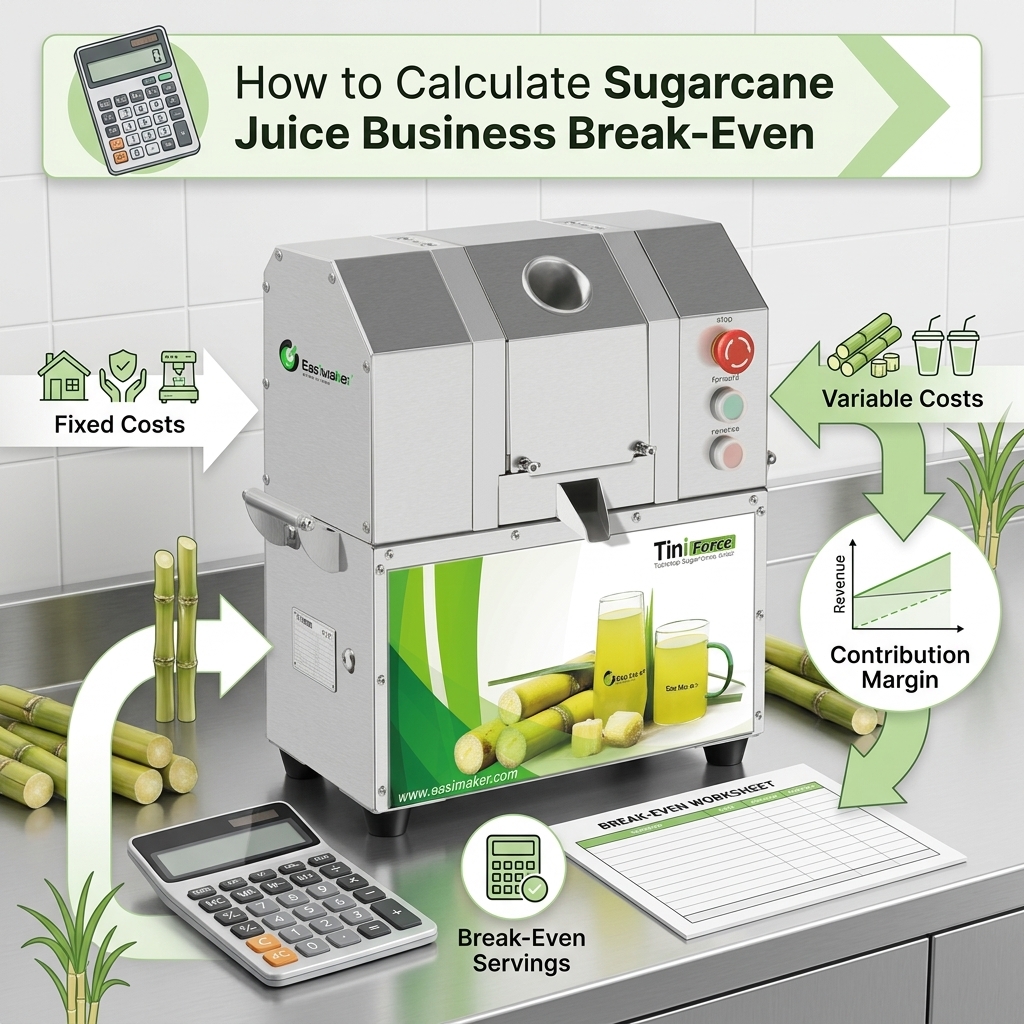
Infographic showing the formula for calculating sugarcane juice business break-even

The sugarcane juice business break-even point is the sales level at which total revenue equals total costs. At this point, the business has covered its operating expenses but has not yet generated operating profit.

Use this formula:

Break-even servings = Total fixed costs ÷ Contribution margin per serving

To calculate the break-even point in sales revenue:

Break-even revenue = Break-even servings × Selling price per serving

The contribution margin is the selling price minus the variable cost of producing and selling one serving. This calculation is more useful than comparing machine price with daily sales because it includes the costs that change with every cup.

For a reliable model, calculate the result by day, month, and year. Also separate one-time startup investment from recurring operating costs so you can understand both operating break-even and investment payback.

Identify Fixed and Variable Costs

Infographic showing the formula for calculating sugarcane juice business break-even

The quality of a sugarcane juice break-even analysis depends on how completely you list costs. Start with two categories: fixed costs and variable costs.

Fixed costs

Fixed costs generally remain stable during the period being analysed, even when sales volume changes. They may include:

  • Shop, kiosk, or market-stall rent
  • Base salaries or guaranteed wages
  • Business registration, permits, and recurring service fees
  • Equipment depreciation or monthly finance payments
  • Insurance, accounting, software, and communications
  • Basic utilities that do not vary significantly with output
  • Planned maintenance allowances

Some costs are semi-fixed. For example, electricity may include a fixed connection charge plus a usage charge. Estimate each part separately where possible.

Variable costs

Variable costs increase as more servings are sold. Include:

  • Raw sugarcane consumed per serving
  • Cups, lids, straws, bags, labels, and other packaging
  • Ice, water, flavouring, or optional ingredients
  • Payment processing fees based on transaction value
  • Sales commissions or delivery charges
  • Waste and spoilage associated with each serving

Do not overlook startup items such as the juicer, preparation table, water system, signage, initial stock, transport, installation, and staff training. These may not all enter the monthly operating break-even formula, but they matter when calculating payback and overall business ROI.

For a broader equipment budget, review this guide to sugarcane juicer cost and business budgeting.

Calculate Contribution Margin per Serving
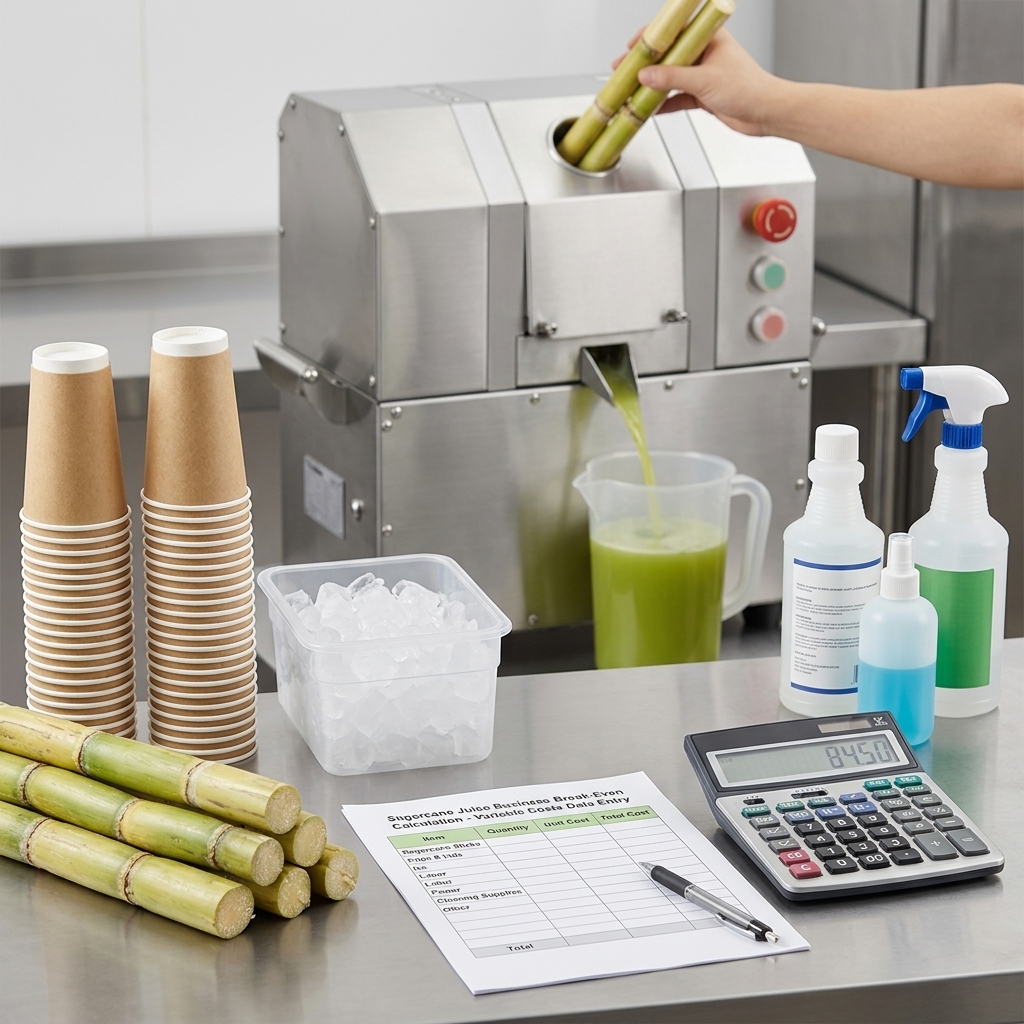
Sugarcane juice business cost inputs arranged for a break-even calculation

Contribution margin shows how much of each sale is available to cover fixed costs and then produce profit.

Contribution margin per serving = Selling price − Variable cost per serving

For example, suppose a business sells one standard cup for 3.00 in its local currency. If sugarcane, packaging, ice, transaction fees, and expected waste total 1.20 per cup, the contribution margin is 1.80.

Do not use the raw purchase price of sugarcane alone. Measure or estimate the amount of usable cane required for the serving size, account for trimming and extraction waste, and update the figure when supplier prices change. If the menu has several sizes or products, calculate a separate margin for each one.

For a mixed menu, use a weighted average contribution margin. This requires an estimated sales mix, such as the proportion of small, regular, large, and add-on sales. If the sales mix is uncertain, prepare a low-margin and high-margin scenario rather than relying on one optimistic average.

Equipment selection affects the cost model indirectly. A machine that does not match the intended service volume may create excess labour, slower service, avoidable downtime, or unnecessary capital cost. Use the commercial sugarcane juicer selection guide to compare real output needs, workspace, power supply, cleaning, and technical support before finalising the investment.

Worked Break-Even Example
Financial planning worksheet and juice cups for a sugarcane business break-even example

The following example is illustrative only. Replace every amount with local prices, taxes, wages, rent, and operating conditions.

InputIllustrative amount
Monthly fixed costs5,400
Selling price per serving3.00
Variable cost per serving1.20
Contribution margin per serving1.80

Using the formula:

5,400 ÷ 1.80 = 3,000 servings per month

The business must therefore sell 3,000 servings per month to cover the listed fixed costs under these assumptions. If it operates 26 days per month, the daily break-even target is approximately:

3,000 ÷ 26 = 115.4 servings per operating day

Because a business cannot sell a fraction of a serving, the practical target would be at least 116 servings per day, subject to opening hours and demand patterns. Break-even revenue is:

3,000 × 3.00 = 9,000 per month

If the operation sells 4,000 servings at the same assumptions, the monthly operating profit before tax, owner drawings, loan interest, and other excluded items would be:

(4,000 × 1.80) − 5,400 = 1,800

This is not the same as total investment ROI. It is an operating-profit example and should be adjusted for the items included in your own accounting method.

Use Realistic Sales and Operating Assumptions

Financial planning worksheet and juice cups for a sugarcane business break-even example

A break-even result is only as useful as the assumptions behind it. Estimate sales by location, opening day, season, weather, service speed, menu price, and available staff rather than using maximum machine output as expected demand.

Build a daily operating model that includes:

  • Expected customer traffic and conversion rate
  • Average servings per transaction
  • Peak and quiet periods
  • Opening days and hours
  • Stock availability and supplier delivery schedule
  • Service interruptions, cleaning time, and planned downtime
  • Different prices or product sizes

Separate capacity from demand. A juicer may be capable of supporting a target workflow, but the business may not have enough customers to use that capacity. Conversely, a machine that is too small for peak service can create queues and lost sales. Your model should use expected sellable volume, not theoretical production volume.

Raw material planning also affects the result. Review practical guidance on storing sugarcane for fresh juice service to reduce avoidable spoilage and keep purchasing aligned with demand.

For hygiene-related labour, layout, and cleaning time, see the guide to designing a hygienic sugarcane juice workstation. A more efficient workflow may improve saleable service time, but any benefit should be verified with actual operating data.

Connect Break-Even with ROI and Sensitivity Analysis

Sugarcane juice business cost inputs arranged for a break-even calculation

Break-even tells you when operating revenue covers operating costs. ROI asks whether the profit generated is adequate compared with the total investment.

A simple annual operating ROI estimate is:

Annual operating ROI = Annual operating profit ÷ Total invested capital × 100

Total invested capital may include equipment, shipping, installation, site preparation, deposits, permits, opening inventory, signage, and other startup costs. Define whether the calculation includes financing costs, taxes, owner labour, and depreciation. Different definitions can produce different ROI results.

Payback period is another useful measure:

Payback period = Total initial investment ÷ Average monthly cash operating surplus

Use sensitivity analysis to test what happens when important assumptions change. At minimum, model:

  • Lower, expected, and higher daily serving volume
  • Changes in cane and packaging costs
  • Different selling prices and product mixes
  • Seasonal operating days
  • Unexpected repairs or equipment downtime
  • Higher rent, wages, delivery, or payment fees

A useful spreadsheet should show the break-even servings and monthly result for each scenario. This helps you judge whether the business remains viable when actual sales or costs differ from the initial plan.

Practical Ways to Improve the Break-Even Point

Infographic showing the formula for calculating sugarcane juice business break-even

Once the model is complete, the objective is not simply to increase the selling price. Improve the relationship between contribution margin, fixed costs, and reliable sales.

  • Reduce avoidable waste: Match cane purchasing to expected demand, rotate stock, and record actual yield and discarded material.
  • Review serving sizes: Confirm that each size has a clear margin after cane, packaging, ice, and transaction costs.
  • Control fixed overhead: Compare rent, staffing, utilities, and service arrangements with the sales volume the location can support.
  • Protect service uptime: Follow cleaning and maintenance procedures and keep a practical process for responding to faults. The commercial sugarcane juicer troubleshooting guide can help operators identify common issues before they become prolonged interruptions.
  • Choose equipment around the workflow: Consider actual service volume, operator count, cleaning requirements, power supply, footprint, and local support instead of selecting only by purchase price.
  • Track actual results: Record daily servings, sales value, cane purchased, waste, labour hours, downtime, and maintenance cost. Update the model monthly.

The most dependable break-even plan is a living operating document. Recalculate it when supplier prices, rent, wages, menu prices, opening hours, or equipment arrangements change.
How to Calculate Sugarcane Juice Machine Break-Even

Table of Contents

Calculate a sugarcane juice machine break-even point by dividing total startup investment by contribution per cup, then test the result against realistic daily sales, operating days, waste, and maintenance costs.

The Sugarcane Juice Machine Break-Even Formula

Calculator and cost worksheet used to calculate sugarcane juice machine break-even

To calculate a sugarcane juice machine break-even point, first find the contribution earned from each cup sold, then divide your total startup investment by that amount.

Break-even cups = Total startup investment / Contribution per cup

Contribution per cup = Selling price per cup – Variable cost per cup

The result is the number of cups you must sell before the initial investment is recovered. To turn this into a time estimate, divide break-even cups by the realistic number of cups you expect to sell per operating day. This is a planning estimate, not a guaranteed result: customer demand, local pricing, cane quality, staffing, waste, rent, and downtime can all change the outcome.

For an established operation, it is often more useful to calculate a monthly break-even point as well. In that case, divide monthly fixed operating costs by contribution per cup. This shows the cups required each month to cover recurring costs after the initial purchase has been made.

Define the Costs in Your Calculation

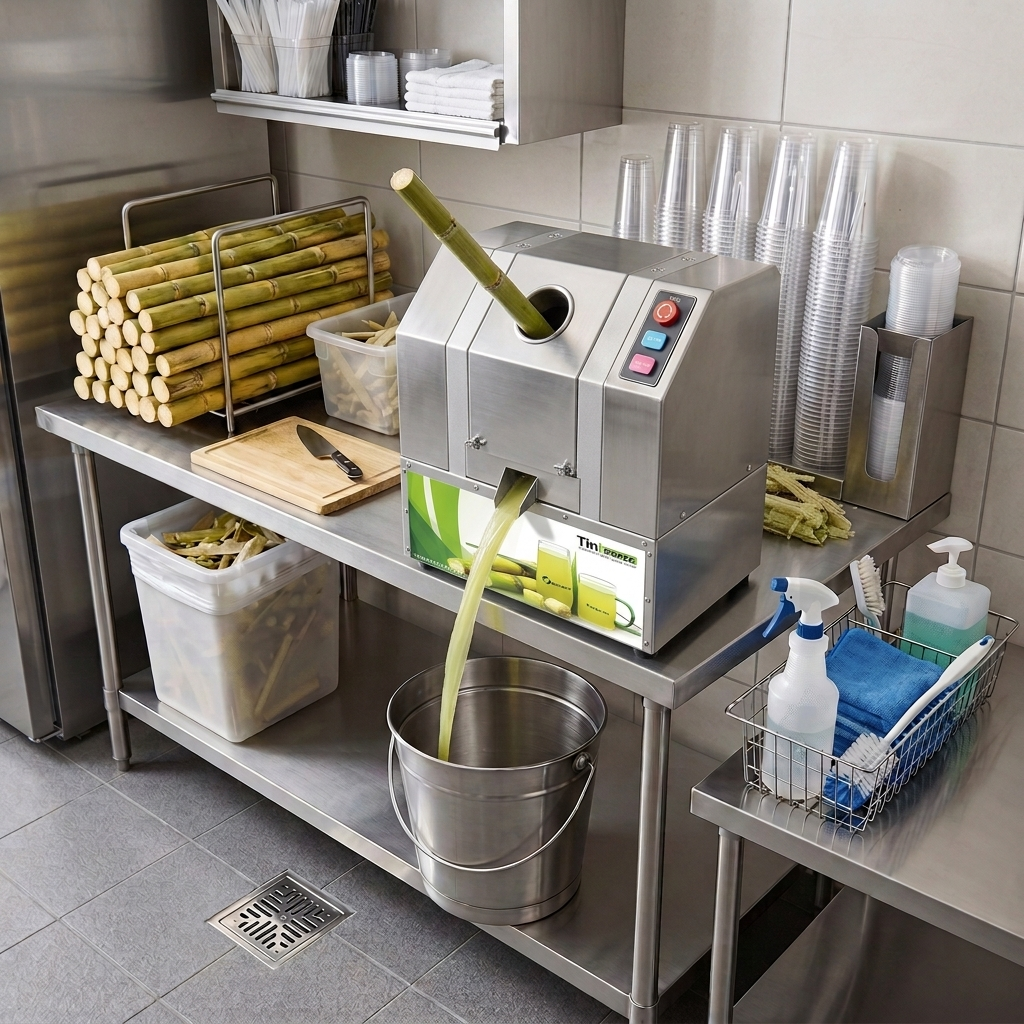
Operating supplies and commercial sugarcane juicer used in a cost calculation

A useful break-even calculation separates one-time startup costs, recurring fixed costs, and costs that rise with every cup sold. Combining all of them in one number can make a result difficult to check or update.

One-time startup investment

  • Commercial sugarcane juice machine purchase price
  • Freight, import duties, local delivery, and installation where applicable
  • Electrical work, water access, drainage, counters, or a kiosk fit-out
  • Initial tools, food-safe containers, cleaning supplies, and opening stock
  • Permits, deposits, signage, and point-of-sale setup where relevant

Recurring fixed costs

  • Rent or site fees
  • Base payroll or management costs
  • Insurance, licences, communications, and accounting
  • Scheduled maintenance allowance and general overhead

Variable cost per cup

  • Sugarcane used for that serving, including an allowance for trimming and unusable material
  • Cup, lid, straw or alternative, napkin, and seal if used
  • Ice, flavour additions, fruit, lemon, or other ingredients sold with the drink
  • Payment processing cost when it varies with the transaction value
  • Labour directly tied to making and serving each drink, if you choose to model it per cup

Do not assume the machine price is the complete investment. A commercial machine is one part of a working service station. For a closer view of unit economics, see this guide to calculating juice cost per cup for commercial operations.

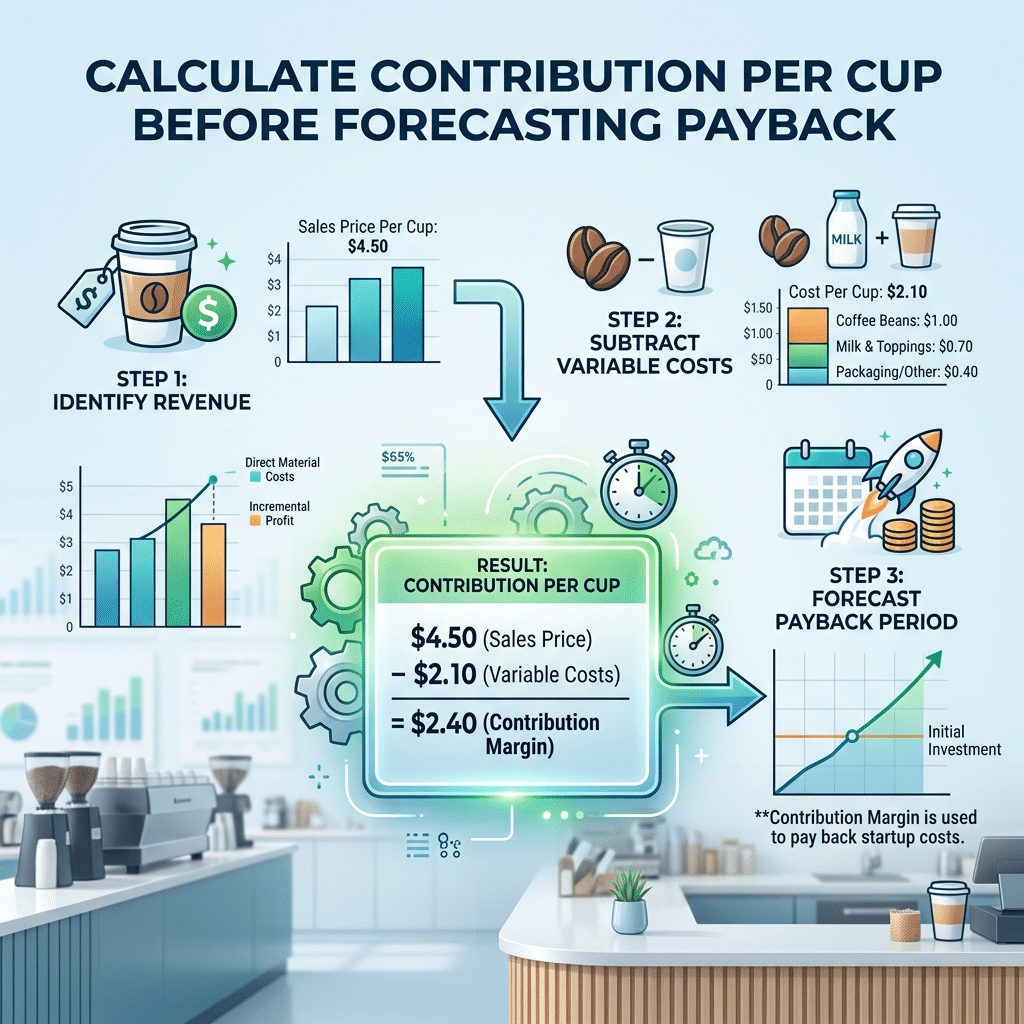
Calculate Contribution Per Cup Before Forecasting Payback

Calculate Contribution Per Cup Before Forecasting Payback

Contribution per cup is the amount remaining from each sale to cover fixed costs and recover startup investment. It is not the same as gross sales and should not be confused with final net profit.

Start with the actual menu price customers pay. Then subtract the variable cost of producing and serving one cup. Where a recipe includes different cup sizes or add-ons, calculate each version separately. A large serving with more cane, ice, packaging, and preparation time may have a different contribution from a standard serving.

Use a recent purchasing period to establish the cane cost. Record the quantity purchased, usable production after trimming, and total cups served. This helps avoid basing the calculation on an ideal extraction assumption. Cane condition, stalk diameter, supplier consistency, preparation method, and operator practice can affect usable output. If you do not yet have operating records, use conservative assumptions and review them after the first weeks of trade.

Include a modest allowance for product loss, remakes, samples, spoilage, and unsold prepared ingredients. It is better to identify uncertainty in the model than to hide it inside an optimistic sales forecast. Review packaging and ingredient costs regularly because they can change independently of the menu price.

When comparing machine options, use the same selling price, ingredient assumptions, and operating hours for each option. The decision then becomes clearer: whether a machine’s purchase cost, workflow, cleaning time, and expected service capacity fit the intended outlet.

Work Through a Practical Break-Even Example

The following example shows the method only. Replace every number with your own supplier quotes, recipe costs, local selling price, and site costs.

Assume a new juice counter has a total startup investment of 12,000 in its local currency. This includes equipment and the direct costs needed to begin service. The standard drink sells for 5.00. Cane, packaging, ice, minor ingredients, and transaction-related variable costs total 2.00 per cup.

  • Selling price per cup: 5.00
  • Variable cost per cup: 2.00
  • Contribution per cup: 3.00
  • Total startup investment: 12,000

Break-even cups = 12,000 / 3.00 = 4,000 cups

If the outlet sells an average of 40 cups per day, the simple investment recovery estimate is 100 operating days. At 20 cups per day, it becomes 200 operating days. At 60 cups per day, it becomes about 67 operating days. These figures do not include recurring fixed costs unless they were included in the startup investment, so they should not be presented as a profit forecast.

For a fuller monthly test, assume monthly fixed costs are 3,000 and contribution remains 3.00 per cup. The business needs 1,000 cups per month to cover those monthly fixed costs: 3,000 divided by 3.00. If it operates 25 days per month, that is 40 cups per day before considering recovery of the original investment.

Use realistic local demand rather than choosing a daily sales number simply because it produces an attractive payback period. A sensible forecast can use a low, expected, and high sales case.

Test Sales Volume and Operating Assumptions

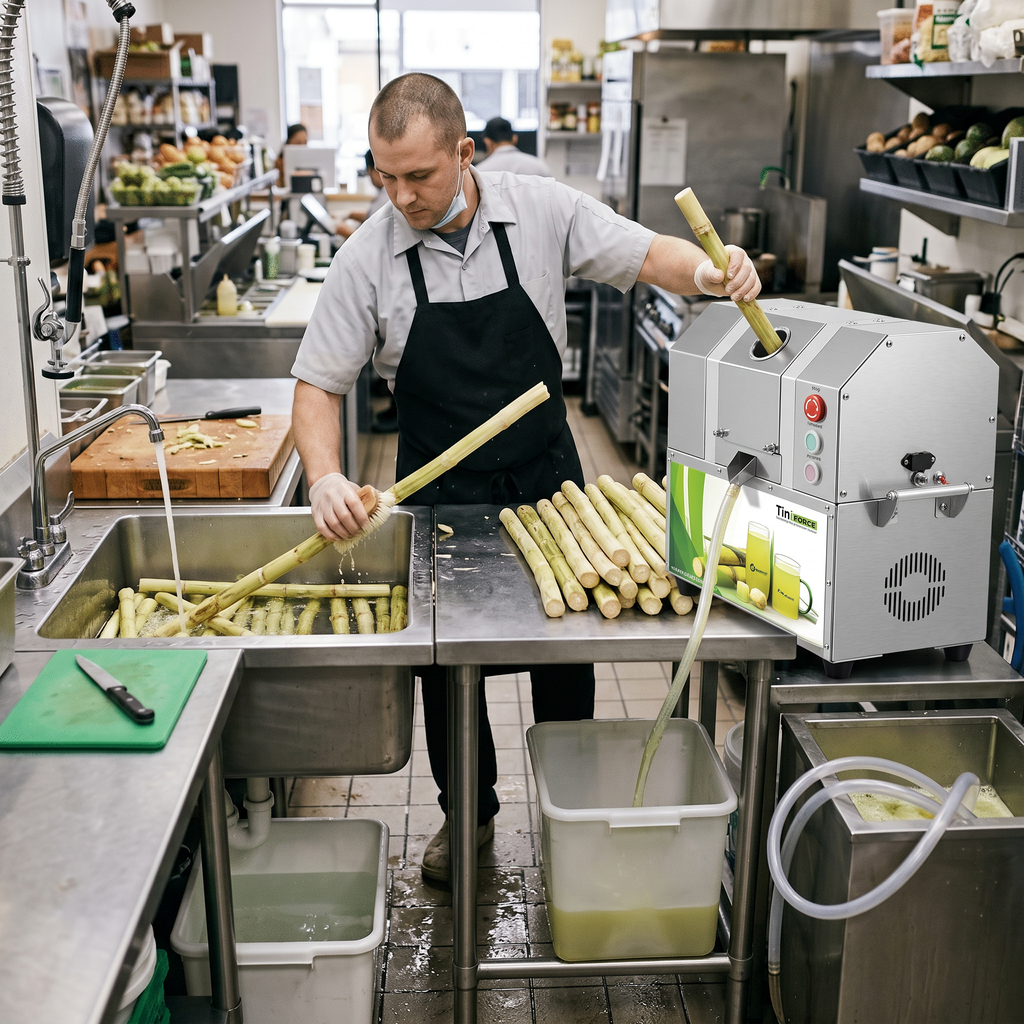
Operator workflow at a commercial sugarcane juice machine

The quality of a sugarcane juice machine break-even calculation depends more on its assumptions than on the formula. Sales volume is often the largest unknown, particularly for a new kiosk, restaurant menu, market stall, or distributor-supported launch.

Build at least three cases:

  • Low case: slower footfall, a reduced conversion rate, weather disruption, or a gradual customer adoption period.
  • Expected case: the daily sales level supported by your location, trading hours, menu fit, and staff capacity.
  • High case: strong demand during peak periods, events, or a successful repeat-customer base.

Use the expected case for purchase planning and keep the low case visible when assessing cash requirements. Also consider seasonality. A location may have high demand in warm months and substantially lower demand in other periods. A daily average drawn only from peak season can distort the decision.

Machine workflow matters because a forecasted sales volume must be operationally achievable. Review cane washing and trimming, feeding, juice collection, drink assembly, payment, cleaning between service periods, and staff handover. A machine with an appropriate workflow for the site can help the team serve demand consistently, while an oversized or poorly matched setup may add cost without solving the main constraint.

Before committing, use a structured purchasing discussion. This list of questions to ask a sugarcane juicer manufacturer can help you confirm electrical requirements, cleaning access, parts planning, and the operating conditions that affect your model.

Ways to Improve the Break-Even Point Without Distorting the Model

A lower break-even point usually comes from increasing contribution per cup, reducing avoidable startup costs, or improving sustainable sales volume. The right action depends on what is limiting the operation.

  • Price with local evidence: compare the full offer, serving format, site position, and competitors. Do not raise prices in the spreadsheet without checking whether customers will accept them.
  • Control portion and recipe standards: document cup size, ingredients, ice policy, and serving method so staff can produce a consistent product and cost.
  • Reduce avoidable waste: improve stock rotation, cane preparation, and purchasing quantities. Track waste separately instead of assuming it does not exist.
  • Protect uptime: establish daily cleaning, inspection, and parts procedures. Unplanned downtime can reduce sales and create avoidable expense.
  • Plan labour around demand: align staffing with peak periods while maintaining practical cleaning and food-handling routines.
  • Use add-ons carefully: only add menu items or formats that fit the available preparation space, operator skill, and customer demand.

Break-even should be reviewed after launch. Compare planned and actual cups sold, average selling price, variable cost, waste, and operating days. Update only the assumptions supported by records. For wider launch planning, the guide on starting a sugarcane juice business covers practical commercial considerations beyond the machine purchase.

Use Break-Even Analysis Before Buying Equipment

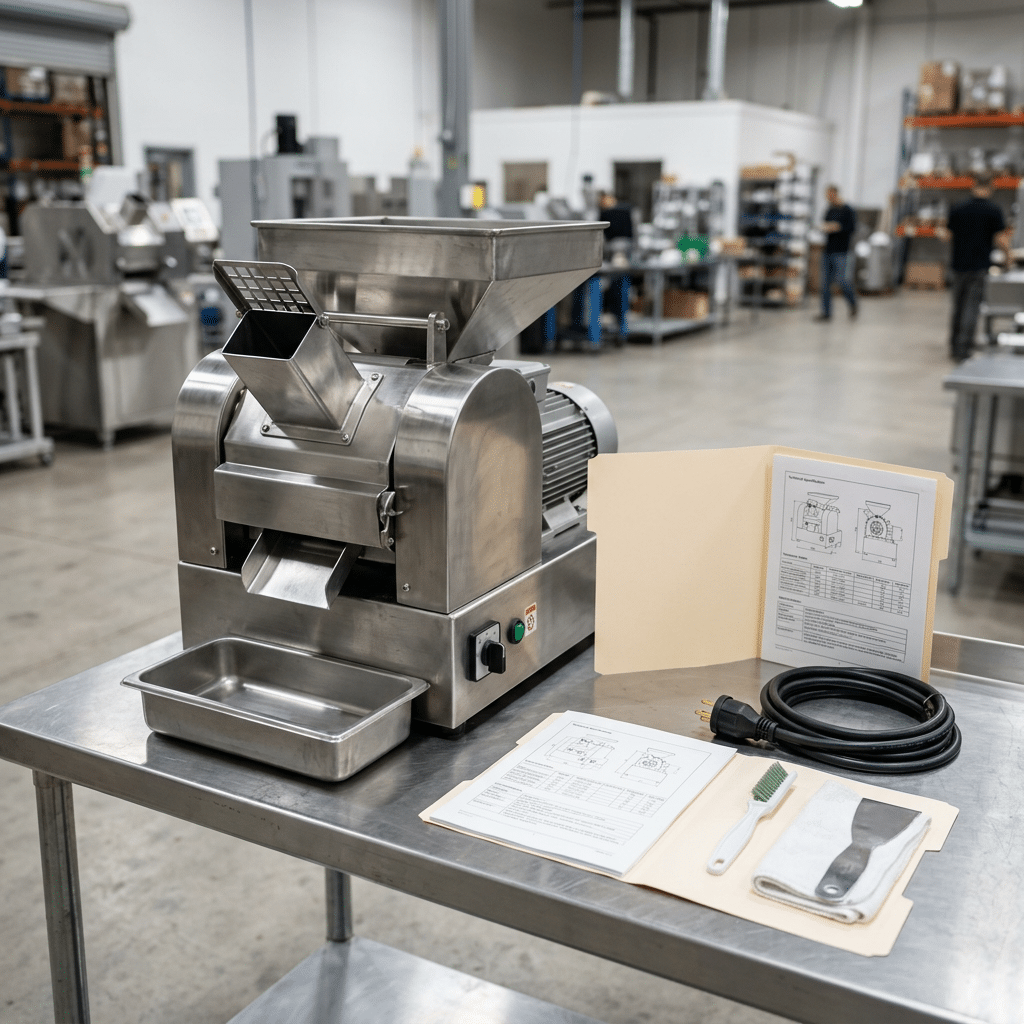
Commercial sugarcane juicer evaluated with operating and support documentation

Use the calculation to compare complete operating options, not just quoted machine prices. A lower purchase price can be less suitable if the machine does not match local electrical supply, cane type, daily workflow, cleaning requirements, service access, or expected demand. Conversely, a higher initial investment should be tested against the actual operational benefit it provides, rather than assumed to pay back automatically.

Ask suppliers for the information needed to make the model specific: supplied configuration, electrical compatibility, installation considerations, cleaning routine, available spare parts, warranty terms, and support process. Do not use unsupported extraction, capacity, or payback figures in your calculation. Where an input is uncertain, label it and test a range.

For distributors and brands considering a private-label programme, additional costs may include product configuration, packaging, documentation, market-specific electrical requirements, inventory, and after-sales support. The OEM sugarcane juicer guide for distributors and brands explains the planning questions that should sit alongside a commercial forecast.

A sound model is simple enough to update, conservative enough to withstand normal variation, and detailed enough to support a purchasing decision. Keep source quotes and operating records with the worksheet so each assumption can be checked later.